Does Razorpay Work in China? Supported Countries, the Payment License & Cross-Border Payer Data
Razorpay is India's payment gateway and aggregator — it settles to Indian businesses in INR and is available in India, Malaysia, Singapore and the United States, with mainland China absent. It holds no PRC payment license, so it cannot be the licensed acquirer for mainland-China payments — a licensed activity under State Council Order No. 768 — and a payer's card and account data sent offshore is a PIPL cross-border transfer. A compliance-first look at the supported-markets list, the payment-license gate, the cross-border payer-data duties, and the lawful China-facing path.
Does Razorpay work in China?
Razorpay is an India-licensed payment gateway: it settles to Indian businesses in INR, onboards merchants with Aadhaar and PAN, and is available in India, Malaysia, Singapore and the United States — mainland China is not one of them. So the first answer is that Razorpay does not sign up a mainland-based business as the merchant on record; mainland China surfaces in its international materials only as a settlement currency a buyer might pay in, never as a place a merchant can register to acquire payments.
Because availability is settled, the real question for a China-facing checkout is a licensing one, not a speed one. Acquiring payments from the public in the mainland is a licensed activity: under the Regulations on the Supervision and Administration of Non-Bank Payment Institutions (State Council Order No. 768, in force May 1, 2024), a foreign non-bank provider that wants to serve mainland users with cross-border payments must first establish a licensed non-bank payment institution inside China. On top of that, a payer's card and account data sent to an offshore gateway is a PIPL cross-border transfer of sensitive personal information, with domestic settlement and data-residency duties under Order No. 768 and the Cybersecurity Law Article 39 (formerly Article 37). The lawful route runs through a licensed China payment institution and domestic methods — never around a block.
On payments our role is lighter and advisory: 21YunBox does not issue or hold a China payment license and is not a payment institution. We map the licensed-local path and your PIPL and licensing exposure, help you localize the checkout onto a compliant collection option, and deliver the China-facing storefront in-country on ICP-filed infrastructure. We never use or suggest circumvention. Treat the specifics as a risk to confirm with counsel.
What Razorpay's own documentation says about China
| Fact | Primary source |
|---|---|
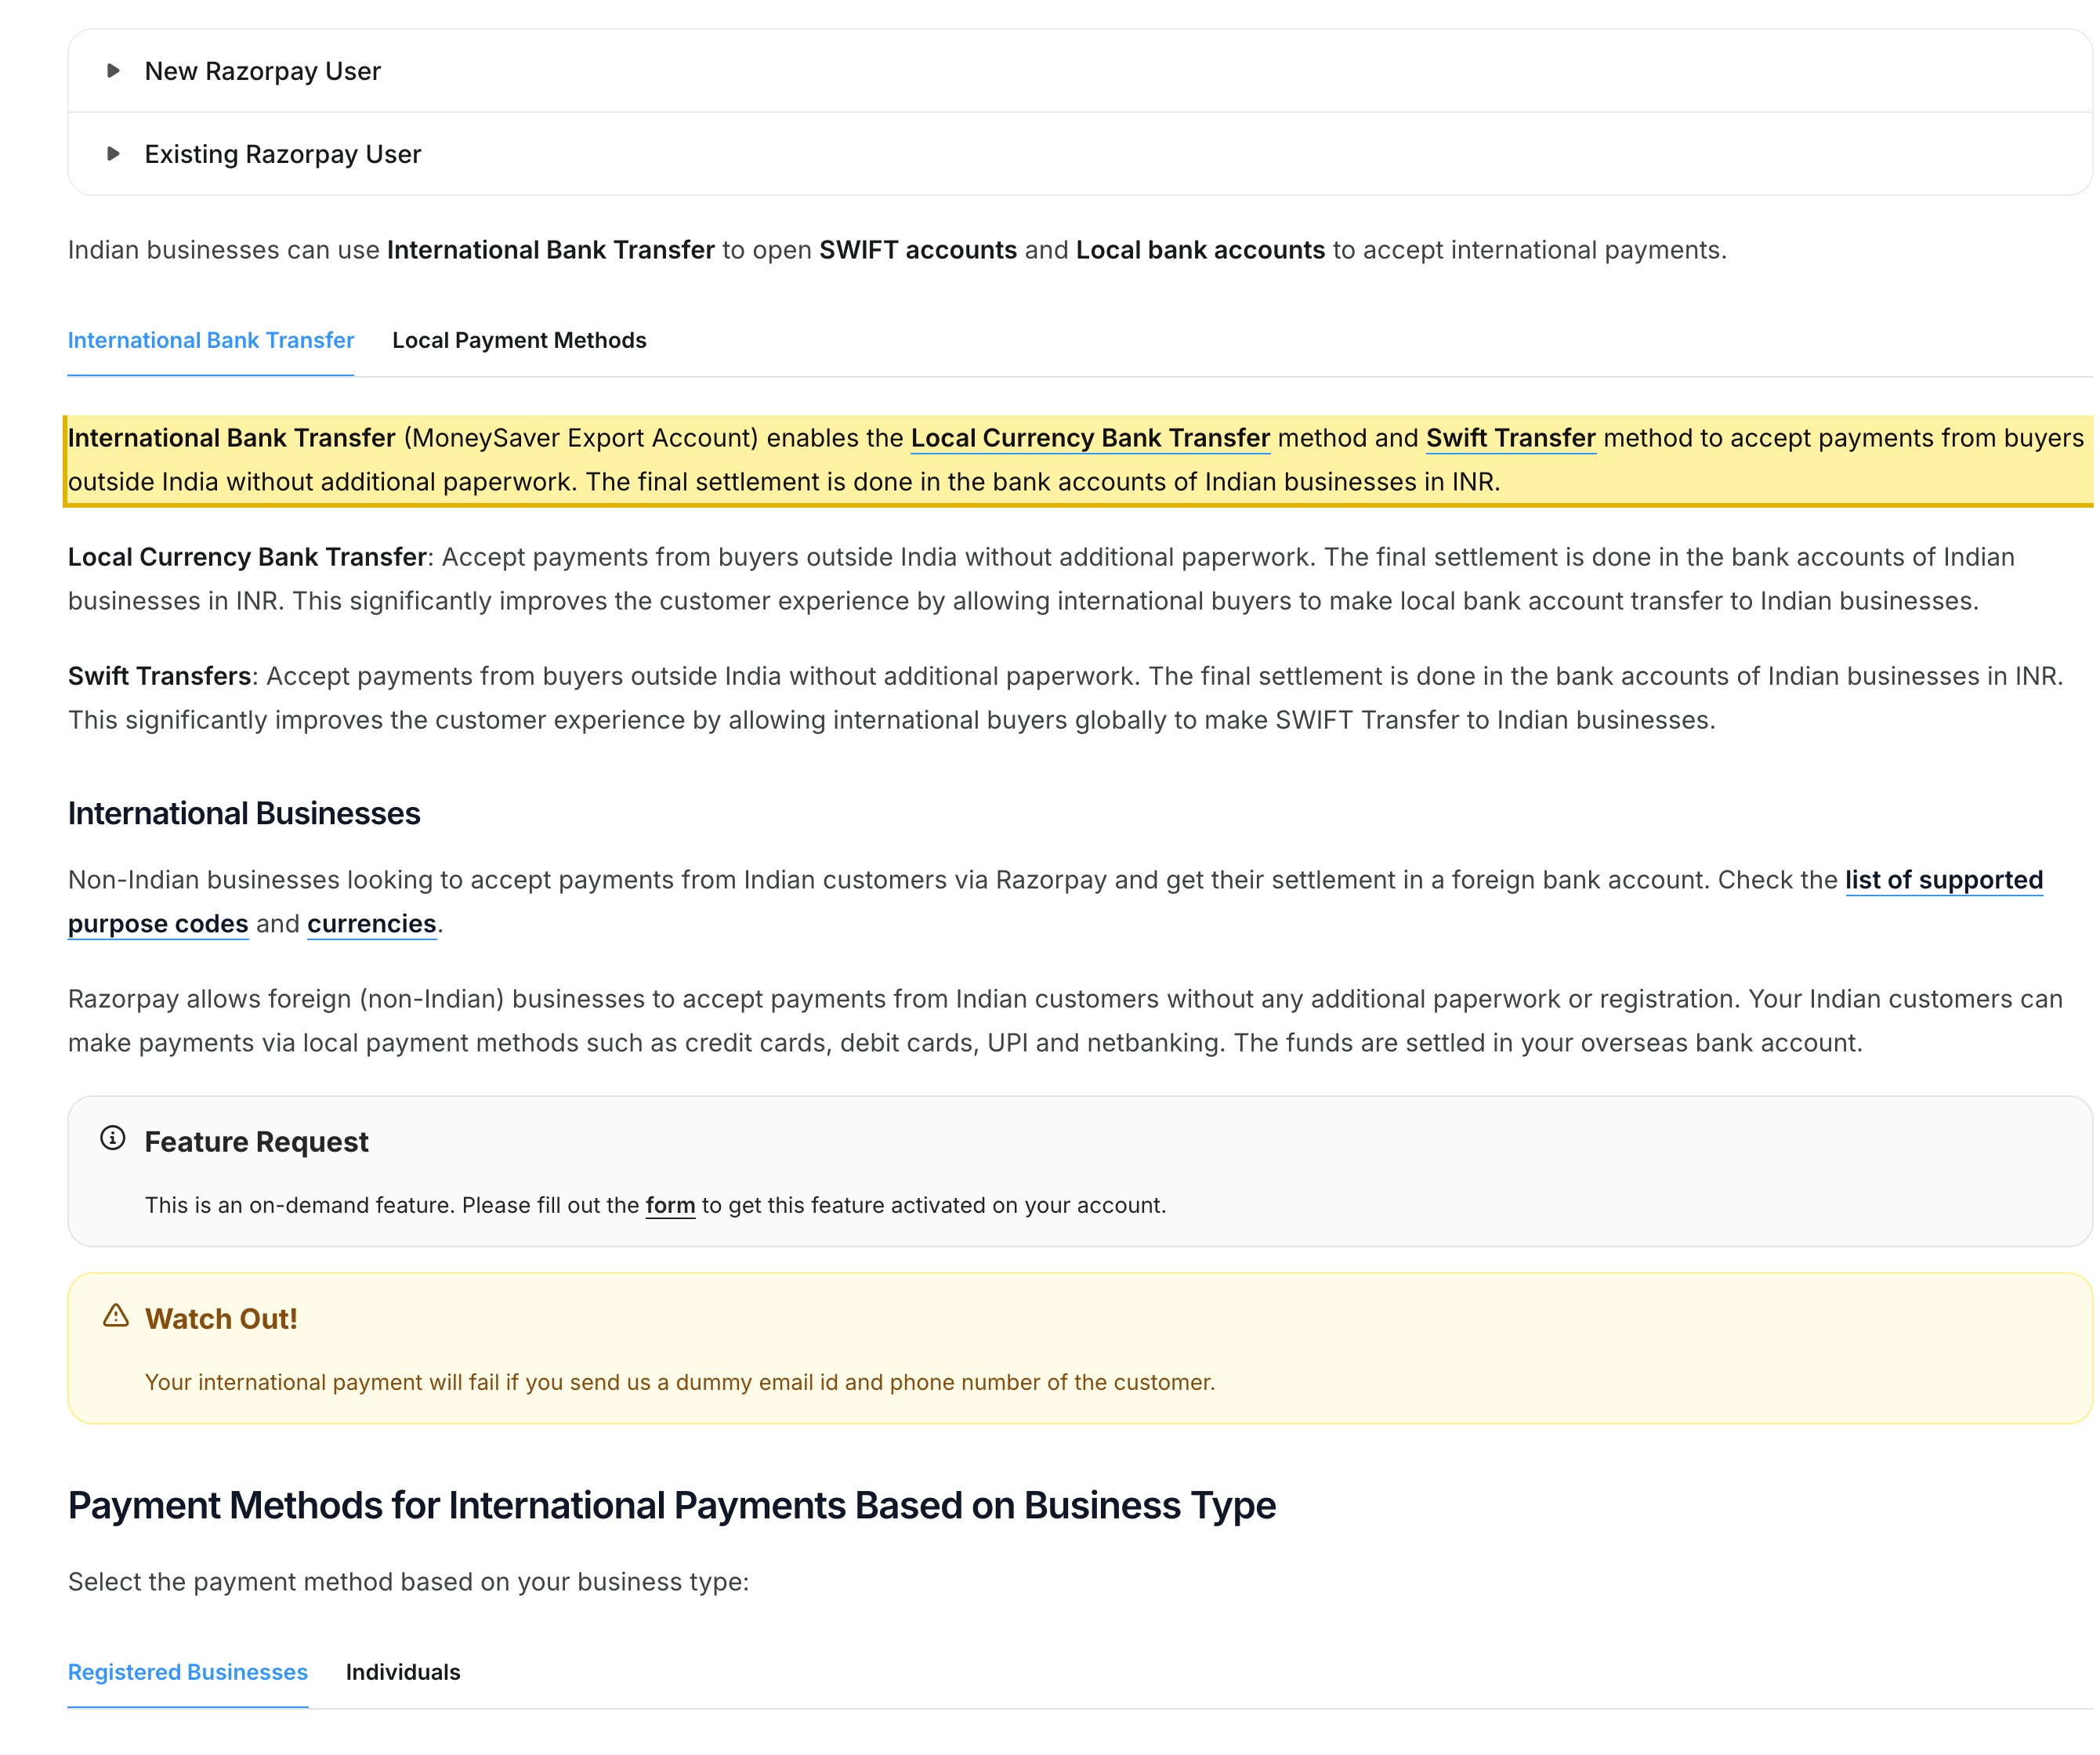
| Razorpay settles to Indian businesses and does not serve mainland-China merchants. Razorpay's international-payments documentation states, “The final settlement is done in the bank accounts of Indian businesses in INR,” and lists the product as available in India, Malaysia, Singapore and the United States. Mainland China is absent from that list, so a mainland-based business cannot onboard as a Razorpay merchant to acquire payments there. | Razorpay, “About International Payments” documentation (razorpay.com), retrieved 2026-10-14 |
| Razorpay merchant onboarding is built around Indian identity and tax documents. The same documentation's new-merchant KYC step “Requires Aadhaar and PAN card” — India's national identity and tax identifiers — and the flow is framed for Indian registered businesses. A business in mainland China holds neither an Aadhaar nor a PAN, so it cannot complete Razorpay merchant onboarding. | Razorpay, “About International Payments” documentation (razorpay.com), retrieved 2026-10-14 |
| Acquiring payments from the public in mainland China requires a China payment license. China's Regulations on the Supervision and Administration of Non-Bank Payment Institutions (非银行支付机构监督管理条例, State Council Order No. 768, in force May 1, 2024) provide in Article 2 that a non-bank institution outside China that intends to provide cross-border payment services to users within the mainland must establish a non-bank payment institution within China — i.e., hold a payment business license (支付业务许可 / 支付牌照) approved by the People's Bank of China. | Regulations on the Supervision and Administration of Non-Bank Payment Institutions, State Council Order No. 768, Art. 2, promulgated 2023-12-09, in force 2024-05-01 |
| A payer's card and account data sent offshore is a PIPL cross-border transfer of sensitive personal information. Financial-account information is sensitive personal information under PIPL (Article 28); sending a mainland payer's card or account identifiers and order records to infrastructure outside China triggers Articles 38–40 — notice, a separate consent distinct from the agreement to buy, and one transfer mechanism (a CAC security assessment, the CAC standard contract, or certification). | Personal Information Protection Law of the PRC, Articles 28 and 38–40 |
Sources verified by the 21YunBox compliance team on 2026-10-14.
For a mainland-China audience, the first question about Razorpay is not how fast its checkout renders or how quickly a card authorizes — it is that Razorpay is an Indian payment gateway, and the business it signs up and settles to is an Indian one. Razorpay is India’s payment gateway and aggregator: online card and UPI acceptance, a merchant dashboard, settlement and the payer and order records behind it. Its own international-payments documentation lists the product as available in India, Malaysia, Singapore and the United States; it settles collected funds “in the bank accounts of Indian businesses in INR,” and its merchant onboarding “Requires Aadhaar and PAN card” — India’s national identity and tax identifiers. Mainland China is not one of the markets Razorpay serves, and in fact it appears in Razorpay’s materials only as a settlement currency (the renminbi) a buyer might pay in, never as a place where a merchant can sign up. So for a China-facing product the starting point is plain: Razorpay is not a way to be the merchant on record acquiring money from mainland customers.
Because availability is already settled, the decision moves to a different axis — a regulatory one, and specifically a licensing one. Accepting payments from the public in mainland China is a licensed activity, not a technical integration, and none of the gates that decide it is measured in milliseconds: whether a foreign provider may acquire mainland payments at all without a China payment license; whether the payer’s card and account details — and the customer personal information a checkout carries — once sent to infrastructure outside the mainland, make a lawful cross-border transfer under PIPL; and, underneath both, whether the China-facing checkout or storefront that carries the payment is itself licensed (ICP-filed) and served in-country. The lawful way to take money from Chinese customers runs through those gates — never around a block, and never through circumvention of any kind.
Razorpay in China at a glance
| What decides it | In Razorpay's own terms — and China's law |
|---|---|
| What it is | Razorpay is India's payment gateway and aggregator — online card and UPI acceptance, settlement, a merchant dashboard, and the payer and order records behind them. It is licensed and operated for India (with regional arms in Malaysia, Singapore and the United States); there is no Razorpay payment entity or China payment license inside mainland China. |
| Can a mainland-China business use it? | No. Razorpay's own international-payments documentation lists it available in India, Malaysia, Singapore and the United States; it settles to Indian businesses in INR and onboards merchants with Aadhaar and PAN. Mainland China is absent from the markets served — a business there cannot open a Razorpay account to acquire payments as the merchant on record. |
| The payment-license gate (支付牌照) | Acquiring and settling payments as an institution inside the mainland needs a payment business license. Under the Regulations on the Supervision and Administration of Non-Bank Payment Institutions (State Council Order No. 768, in force May 1, 2024), a non-bank institution outside China that intends to provide cross-border payment services to users within the mainland must establish a non-bank payment institution within China (Article 2). A foreign provider without one cannot acquire mainland payments directly. |
| Payer card & customer data | A checkout carries the payer's card or account identifiers, name and order record. Financial-account information is sensitive personal information under PIPL (Article 28); sent to infrastructure offshore it is a cross-border transfer (Articles 38–40): notice, a separate consent, and one transfer mechanism. Order No. 768 also requires domestic processing, settlement and storage (Article 19), with in-China storage for CII operators and large-volume handlers (Article 33; Cybersecurity Law Article 39 (formerly Article 37)). |
| The lawful path | Collect through a licensed China payment institution and the domestic payment methods your customers use, with the China-facing storefront delivered in-country on an ICP-filed footing. 21YunBox maps that path and delivers the storefront — on payments its role is advisory, not a license: we do not issue or hold a payment license, and we never use or suggest circumvention. |
Availability: Razorpay is an India-licensed gateway, not a mainland-China acquirer
Razorpay’s position is set on its own documentation, not by a load-time test. Its About International Payments page lists the product as available in India, Malaysia, Singapore and the United States, and the half of the flow that signs up and pays out a merchant is explicitly Indian: the funds Razorpay collects are settled “in the bank accounts of Indian businesses in INR,” and the new-merchant onboarding step “Requires Aadhaar and PAN card” — the national identity and tax numbers an Indian business holds and a mainland-Chinese business does not. A business based in the mainland therefore cannot open a Razorpay account to acquire card payments there as the merchant on record.
The one place mainland China surfaces at all in Razorpay’s international materials is as a currency a customer might pay in — the renminbi sits in the supported-currencies table — not as a country where a merchant can register. That distinction is the whole point. A foreign gateway that lets overseas buyers pay in many currencies is still settling to a merchant somewhere, and for Razorpay that somewhere is an Indian (or other named-market) entity, not a mainland-China one.
That makes the usual “does the checkout load from Shanghai?” framing beside the point. Whether a page happens to render on a given day is not the question — Razorpay does not sign up a mainland-based business as the merchant of record, so there is no compliant acquiring relationship to speak of for collecting mainland payments through Razorpay in the first place. For that reason this page publishes no first-party China latency figure for Razorpay: speed is the wrong axis for a service that does not acquire for a mainland business at all. And to be unambiguous — there is no lawful route around that, and 21YunBox neither provides nor suggests circumvention of any kind. The productive question is a different one: how to take payments from Chinese customers lawfully.
The licensing gate: a foreign provider cannot acquire mainland payments directly
Suppose you do want to charge customers in mainland China. The first gate is not which SDK you wire in — it is whether a foreign provider may acquire mainland payments at all. Accepting payments from the public is a licensed activity in China, governed at the top level by the Regulations on the Supervision and Administration of Non-Bank Payment Institutions (非银行支付机构监督管理条例, State Council Order No. 768, promulgated December 9, 2023 and in force since May 1, 2024). These Regulations establish the payment business license (支付业务许可, commonly a 支付牌照) that every non-bank payment institution must hold, approved by the People’s Bank of China — and, decisively for an overseas provider, Article 2 provides that a non-bank institution outside the territory of China that intends to provide cross-border payment services to users within the mainland must establish a non-bank payment institution within China, unless the State provides otherwise.
In plain terms: a gateway licensed for India that has not established a licensed non-bank payment institution inside the mainland cannot lawfully acquire payments from mainland users on its own. That is the structural reason a supported-markets list stops where Razorpay’s does, and it is a gate no account setting or integration flag clears. Whether and how Order No. 768 applies to your specific flow — where your merchant entity sits, where funds are acquired and settled, which rails you use — and whether any exception fits your structure, is a risk to confirm with qualified counsel against what you actually ship. One thing is clear up front: 21YunBox is not a payment institution and holds no China payment license, so this door is one we help you map, not one we walk through for you.
The cross-border data story: card, account and customer records are personal information
The second gate is the data. A payment is never just an amount — it carries the cardholder’s name, card or account identifiers, billing details, and an order record tied to a real person. Collected from a user in the mainland and sent to infrastructure outside China, all of that is a cross-border transfer of personal information under China’s Personal Information Protection Law — and because it is financial-account information, PIPL treats it as sensitive personal information (Article 28), with heightened consent and necessity duties. PIPL puts the obligation on the handler — the merchant, not only the gateway: Articles 38–40 require notice, a separate consent distinct from the customer’s agreement to buy, and one transfer mechanism — a CAC security assessment, the CAC standard contract, or certification.
Payment law layers its own residency duties on top. Order No. 768 requires that, where a non-bank payment institution provides payment services for domestic transactions, transaction processing, fund settlement, and data storage be completed within China (Article 19); and for an operator whose systems are designated critical information infrastructure, or that processes personal information above the state-set threshold, the personal information collected and generated in the mainland must be handled within the mainland (Article 33). The same data-localization logic runs through the Cybersecurity Law, whose in-country storage duty for critical information infrastructure now sits at Article 39 (formerly Article 37, renumbered by the 2025 amendment in force January 1, 2026, with its substance unchanged). None of this turns on how fast an authorization returns; it turns on whether the data had a lawful basis to leave the country, and whether it had to stay in the first place. Which of these bite your specific case is a risk to confirm with counsel against what you actually collect and store.
The lawful path — map, localize, deliver (advisory on the license)
There is a lawful way to take money from Chinese customers, and it has a shape: payments are collected through a licensed China payment institution and the domestic methods customers actually use, settlement and data stay on a compliant footing, and the storefront that carries the checkout is licensed and served in-country. The common pattern is to route the China-facing checkout to a licensed local payment institution and the mainland’s dominant domestic payment methods — rather than to acquire directly as a foreign merchant — while Razorpay keeps its place for the India and other markets where it already serves you. Which arrangement fits depends on your entity, your volumes, and your data; settle it with counsel and a licensed local payment partner before you build.
Underneath that choice sits the part 21YunBox owns, and it is worth being honest about how much of it is ours. On payments specifically, our role is lighter and advisory than it is for delivery. 21YunBox does not issue or hold a China payment license and is not a payment institution; the license, and the acquiring relationship, sit with a licensed China payment institution and your counsel, not with us. What we do on that footing is three things. We map the lawful path — a licensed local payment institution and domestic methods — alongside your PIPL, data-residency and licensing exposure, so you know exactly what counsel and a local partner need to confirm before anything ships. We help you localize the China-facing checkout onto it — adopting and integrating that compliant, China-legal collection option in place of a Razorpay flow that cannot acquire in the mainland — while the payer and customer data that must stay in China is kept on a China-resident footing. And we deliver the China-facing storefront or app in-country on ICP-filed infrastructure — the 21YunBox Optimizer, in front of the stack you already run, with no rebuild and no re-platform. What we never do — and what no one lawfully can — is give you a way to acquire mainland payments through a service that does not serve a mainland merchant, or route traffic around any block: we map a lawful collection path and deliver the storefront, and we never use or suggest circumvention of any kind. The result is a China-facing checkout that runs legally and compliantly for your users in China.
Related reading:
- China’s Regulations on the Supervision and Administration of Non-Bank Payment Institutions (Order No. 768)
- Cross-border data transfers under PIPL
- China’s Cybersecurity Law — data localization (Article 39, formerly Article 37)
- How to get an ICP filing for China