Does Klarna Work in China? Supported Markets, the Payment & Consumer-Credit License & Cross-Border Data
Klarna offers its buy-now-pay-later and payment service only in a fixed set of supported markets — and mainland China is not one of them: the mainland is absent from Klarna's own list of available countries. But availability was never the real question. Offering consumer credit (BNPL) or acquiring payments from the public in mainland China are licensed financial activities — payment clearing under State Council Order No. 768, consumer lending under China's financial regulator — and any Chinese consumer's identity, credit and transaction data held offshore by Klarna is a PIPL cross-border transfer of sensitive personal information. A compliance-first look at the supported-markets list, the payment- and consumer-credit-license gate, the cross-border data duties, and the lawful China-facing path.
Does Klarna work in China?
No — Klarna is not offered in mainland China: the mainland is absent from Klarna's own list of available countries, so a mainland consumer cannot be offered a Klarna plan and a mainland business cannot use Klarna to collect from them. And availability was never the real question for a China-facing checkout.
Klarna is an unusual case because it is two regulated things at once — a payment acquirer and a consumer lender (Klarna is itself a licensed bank) — and China licenses both. Acquiring and clearing payments from the public turns on a China payment business license: under the Regulations on the Supervision and Administration of Non-Bank Payment Institutions (State Council Order No. 768, in force May 1, 2024), an offshore provider that wants to serve mainland users cross-border must first establish a licensed non-bank payment institution inside China. Extending consumer credit or installment lending (BNPL) to the public is itself a licensed financial activity supervised by China's financial regulator. Underneath both, the identity, credit-assessment and card data a China checkout carries is sensitive personal information — a PIPL cross-border transfer when it leaves the country, with data-residency duties under Order No. 768 and the Cybersecurity Law Article 39 (formerly Article 37).
On the financial-license side our role is advisory and lighter: 21YunBox is not a payment institution or a lender and holds no China payment or lending license. We map the licensed domestic payment and financing path and your PIPL and licensing exposure, help you localize the checkout onto it, and deliver the China-facing storefront in-country on ICP-filed infrastructure — with your existing Klarna integration left where it serves you. We never use or suggest circumvention. Treat the specifics as a risk to confirm with counsel.
What Klarna's own documentation says about China
| Fact | Primary source |
|---|---|
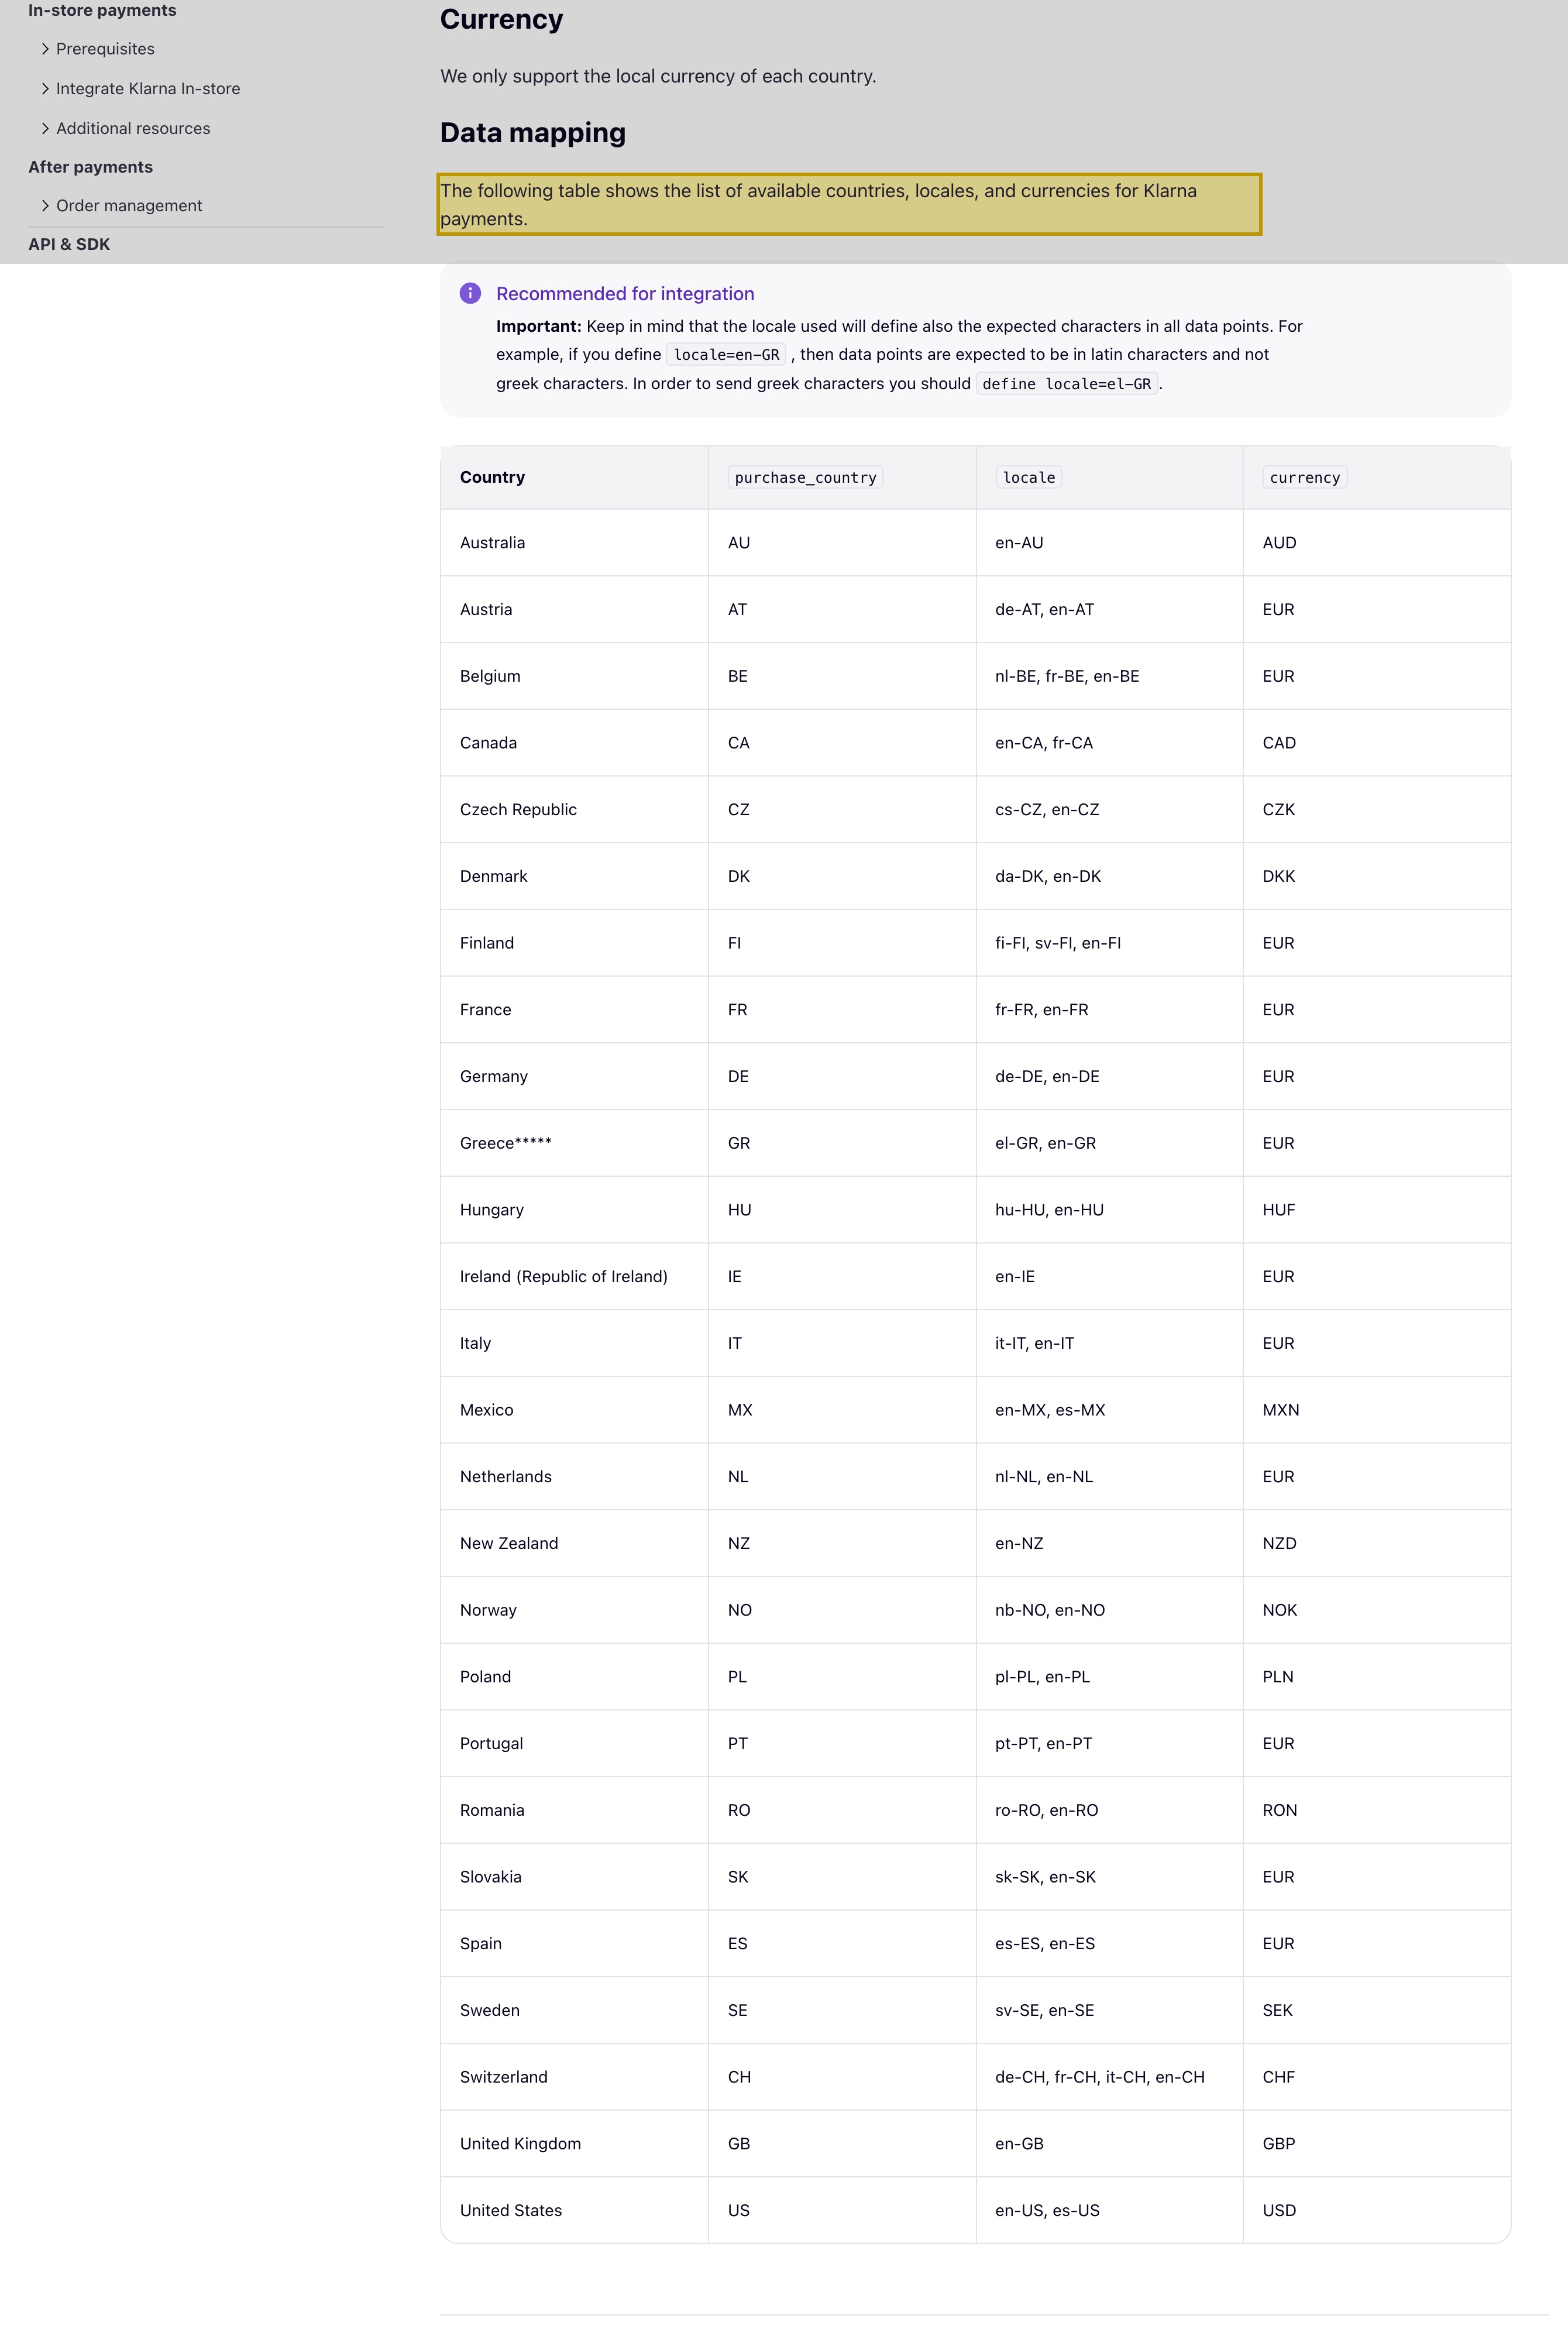
| Klarna is offered only in a fixed set of markets, and mainland China is not among them. Klarna's own developer documentation, on its purchase countries, currencies and locales page, states: “The following table shows the list of available countries, locales, and currencies for Klarna payments,” and the table lists 26 markets — across Europe plus Australia, Canada, Mexico, New Zealand and the United States — with no mainland-China (CN) entry. | Klarna Docs, “Purchase countries, currencies and locales” (docs.klarna.com), retrieved 2026-10-09 |
| Acquiring payments from the public in mainland China needs a China payment business license. China's Regulations on the Supervision and Administration of Non-Bank Payment Institutions (非银行支付机构监督管理条例, State Council Order No. 768, in force May 1, 2024) provide in Article 2 that a non-bank institution outside China that intends to provide cross-border payment services to users within the mainland must establish a non-bank payment institution within China — i.e. hold a payment business license (支付业务许可 / 支付牌照) approved by the People's Bank of China. | Regulations on the Supervision and Administration of Non-Bank Payment Institutions, State Council Order No. 768, Art. 2 (gov.cn), promulgated 2023-12-09, in force 2024-05-01 |
| Settlement and data storage for domestic transactions must stay in China, and localization bites for big or critical handlers. Order No. 768 requires that transaction processing, fund settlement and data storage for domestic transactions be completed within China (Article 19), and where a payment institution is a critical information infrastructure operator or processes personal information above the state threshold, that personal information must be handled within the mainland (Article 33) — the same data-localization logic the Cybersecurity Law sets in Article 39 (formerly Article 37, renumbered by the 2025 amendment in force January 1, 2026). | Regulations on the Supervision and Administration of Non-Bank Payment Institutions, State Council Order No. 768, Arts. 19 and 33 (gov.cn); Cybersecurity Law of the PRC, Art. 39 (formerly Art. 37), retrieved 2026-10-09 |
| A Klarna checkout's identity, credit and card data sent offshore is a PIPL cross-border transfer of sensitive personal information. Financial-account information is sensitive personal information under PIPL (Article 28), carrying heightened consent and protection duties; sending a mainland consumer's identity, credit-assessment and payment data to Klarna offshore triggers PIPL Articles 38–40 — notice, a separate consent distinct from the agreement to pay, and one transfer mechanism (a CAC security assessment, the CAC standard contract, or certification). | Personal Information Protection Law of the PRC, Articles 28 and 38–40 (cac.gov.cn), retrieved 2026-10-09 |
Sources verified by the 21YunBox compliance team on 2026-10-09.
For a mainland-China audience, the first thing to settle about Klarna is not how quickly its checkout renders — it is that Klarna is not offered in mainland China at all. Klarna provides its buy-now-pay-later and payment service only in a fixed set of supported markets, and the mainland is absent from Klarna’s own published list of available countries. A consumer in the mainland cannot be extended a Klarna plan, and a mainland business cannot plug Klarna in to collect from them. So for a China-facing product the starting point is plain: as things stand, Klarna is not a way to finance or collect money from mainland customers.
Because availability is already settled, the decision moves to a regulatory axis — and Klarna makes it a double one. Klarna is not only a checkout; it is itself a licensed bank — Klarna Bank AB, supervised by Sweden’s Finansinspektionen — whose core product is consumer credit. In mainland China both halves of that are licensed financial activities: acquiring and clearing payments from the public turns on a China payment business license, and extending consumer credit or installment lending to the public turns on a domestic financial license of its own. Underneath both sits a data door — the identity, credit-assessment and transaction records a Chinese consumer would generate are personal information, and much of it sensitive. None of these gates is about milliseconds, and none is cleared by circumvention of any kind — 21YunBox neither uses nor suggests any.
Klarna in China at a glance
| What decides it | In Klarna's own terms — and China's law |
|---|---|
| What it is | Klarna is a licensed bank and buy-now-pay-later / payment provider: it extends consumer credit (installments and pay-later) and acquires checkout payments, in a fixed set of supported markets. It holds consumer identity, credit-assessment and transaction data. |
| Is it available in mainland China? | No. Mainland China is absent from Klarna's own list of available countries — 26 markets across Europe plus Australia, Canada, Mexico, New Zealand and the United States. A mainland consumer cannot be offered a Klarna plan, and a mainland business cannot use Klarna to collect from them. |
| The payment-license door (支付牌照) | Acquiring and clearing payments from the public inside the mainland needs a China payment business license. Under the Regulations on the Supervision and Administration of Non-Bank Payment Institutions (State Council Order No. 768, in force May 1, 2024), an offshore non-bank institution serving mainland users cross-border must establish a non-bank payment institution within China (Article 2). |
| The consumer-credit door | Extending consumer credit or installment lending (BNPL) to the public is itself a licensed financial activity in China, supervised by the national financial regulator. An offshore lender cannot offer it to mainland consumers without the requisite domestic license — the same activity for which Klarna holds a banking license at home. |
| Identity, credit & transaction data | A China checkout or credit decision carries identity, credit-assessment and card data — financial-account information is sensitive personal information under PIPL (Article 28). Holding it offshore is a cross-border transfer (Articles 38–40: notice, a separate consent, a transfer mechanism), with domestic-storage duties under Order No. 768 (Article 19) and, for a CIIO or large-volume handler, Cybersecurity Law Article 39 (formerly Article 37). |
| The lawful path | Keep Klarna for your supported markets; put a licensed domestic payment route in front of your China-facing checkout and, where financing is wanted, a licensed domestic installment/consumer-finance option, then file and deliver that checkout in-country. 21YunBox maps the licensing and data exposure with you and your counsel, helps localize onto the licensed domestic path, and delivers the checkout in-country. We are not a payment institution or a lender; the licenses sit with the licensed providers. |
Availability: Klarna is not offered in mainland China
Klarna’s position is set on its own developer documentation, not by a load-time test. Its purchase-countries page says plainly, “The following table shows the list of available countries, locales, and currencies for Klarna payments,” and the table that follows names 26 markets — the Nordics and much of the rest of Europe, plus Australia, Canada, Mexico, New Zealand and the United States. Mainland China is not one of them. Every Klarna payment session has to declare a purchase country from that set, so there is no mainland value to send in the first place.
For a China-facing storefront that settles the opening question: a mainland consumer cannot be offered a Klarna plan, and a mainland business cannot wire Klarna in to collect from them. For that reason this page publishes no first-party China latency figure for Klarna — speed is the wrong axis for a service that is not offered to the mainland at all. The productive question is a different one: how to finance and take payments from Chinese customers lawfully, which runs through licensed domestic rails and never around a block.
The licensing door: payment and consumer credit are both licensed in China
Suppose you still want to finance or collect from customers in mainland China. Klarna is an unusual case, because it is two regulated things at once — a payment acquirer and a consumer lender — and China licenses both.
Payments first. Accepting and clearing payments from the public in the mainland is a licensed activity under the Regulations on the Supervision and Administration of Non-Bank Payment Institutions (非银行支付机构监督管理条例, State Council Order No. 768, promulgated December 9, 2023 and in force since May 1, 2024). They establish the payment business license (支付业务许可 / 支付牌照) every non-bank payment institution must hold, approved by the People’s Bank of China, and Article 2 provides that a non-bank institution outside China that intends to provide cross-border payment services to users within the mainland must establish a non-bank payment institution within China. A provider operating from offshore, without that in-China structure and license, is positioned for cross-border acceptance at most — not for acquiring mainland payments directly.
Then the half that is particular to Klarna: credit. Klarna’s core product is consumer finance — pay-in-installments and pay-later — and Klarna holds a banking license at home for precisely that reason. Extending consumer credit or installment lending to the public is no less a licensed financial activity in mainland China, supervised by the national financial regulator; an offshore lender cannot simply extend BNPL to mainland consumers without the requisite domestic license. So the same product that is a regulated bank offering in Europe would, in China, need a Chinese license to run at all. Whether and how either regime applies to your specific flow — where your entity sits, where funds are acquired and settled, whether you are extending credit — is a risk to confirm with qualified counsel against what you actually ship. One thing is clear up front: 21YunBox is neither a payment institution nor a lender and holds no China payment or lending license, so these are doors we help you map, not ones we walk through for you.
The data door: identity, credit and transaction data sent offshore
Underneath the licenses sits the data, and Klarna’s is among the most sensitive a checkout can touch. To decide a pay-later or installment plan, Klarna gathers a consumer’s identity, contact details, order records and a credit assessment, then keeps the transaction history behind it. For a user in mainland China, all of that is personal information — and financial-account information is sensitive personal information under China’s Personal Information Protection Law (Article 28), which carries heightened consent and protection duties. Held by Klarna in one of its offshore markets, that data has left the country: a cross-border transfer under PIPL, where the handler — you, the merchant, not only Klarna — must give notice, obtain a separate consent distinct from the agreement to pay, and satisfy one transfer mechanism (a CAC security assessment, the CAC standard contract, or certification; Articles 38–40). Above the state thresholds, or where the data is “important data,” China’s data-export security assessment (数据出境安全评估) may apply before anything leaves.
Payment law layers a residency duty on top. Order No. 768 requires that, for domestic transactions, transaction processing, fund settlement and data storage be completed within China (Article 19), with in-China storage of personal information for an operator deemed a critical information infrastructure operator or handling personal information above the state threshold (Article 33) — the same data-localization logic the Cybersecurity Law sets in its Article 39 (formerly Article 37, renumbered by the 2025 amendment that took effect on January 1, 2026, with its substance unchanged). None of this turns on how fast a credit decision returns; it turns on whether the data had a lawful basis to leave the country, and whether it had to stay in the first place. Which of these bite your specific product is a risk to confirm with counsel against what you actually collect.
The lawful path — map, localize, deliver
There is a lawful way to finance and take payments from customers in mainland China, and it has a shape: the money is collected through a licensed domestic payment route and the domestic methods customers actually use; where you want to offer installments, the financing is extended by a licensed domestic consumer-finance provider; the data stays on a compliant footing; and the China-facing storefront that carries the checkout is filed and delivered in-country. Klarna keeps its place in that picture — for the supported markets where it already serves you — rather than being ripped out.
Here is the honest division of labor, because on the financial-license side our role is deliberately light. 21YunBox is not a payment institution, not a lender, and holds no China payment or lending license; the licenses and the acquiring and credit relationships sit with the licensed domestic providers and your counsel, not with us. What we do is three things. We map the lawful path — a licensed domestic payment route, and a licensed domestic installment/consumer-finance option where financing is wanted — together with your PIPL, data-residency and licensing exposure, so you know exactly what counsel and a local partner need to confirm before you build. We help you localize the China-facing checkout onto it, adopting and integrating that compliant, China-legal collection and financing path in place of the Klarna call that cannot run in the mainland. And we deliver the China-facing storefront or app in-country: it is itself a public service in the mainland, so it carries an ICP filing (备案) duty and needs compliant in-country delivery like any other China-facing property — the 21YunBox Optimizer, in front of the stack you already run, with no rebuild and no re-platform. What we never do — and what no one lawfully can — is route you around China’s payment or lending licensing or its data-export rules: we map the lawful path, localize your checkout onto it, and deliver it in-country, and we never use or suggest circumvention of any kind. The result is a China-facing checkout that runs legally and compliantly for your users in China.
Related reading:
- China’s Regulations on the Supervision and Administration of Non-Bank Payment Institutions (Order No. 768)
- Cross-border data transfers under PIPL
- China’s Cybersecurity Law — data localization (Article 39, formerly Article 37)
- How to get an ICP filing for China